The Tesla share price target is a major topic for investors trying to decide whether Tesla, Inc. (NASDAQ: TSLA) can deliver strong returns over the coming years. Tesla is no longer just an electric vehicle manufacturer. Its future valuation also depends on battery storage, artificial intelligence, autonomous driving, robotaxis, and humanoid robots.
However, its high valuation, intense competition, and dependence on future growth make the stock difficult to evaluate.
This guide examines Tesla’s business, financial performance, analyst expectations, technical indicators, and long-term growth opportunities to help investors understand what could drive its share price through 2050.
Contents
- 1. About Tesla, Inc.
- 2. Key Points About Tesla
- 3. Company Fundamentals: Revenue, Earnings, and Valuation
- 4. Technical Analysis of Tesla Stock
- 5. Tesla vs. BYD: Competitive Position
- 6. Pros and Cons of Investing in Tesla
- 7. Tesla Share Price Targets 2026–2030
- 8. What Could Change Tesla’s Forecasts Between 2026 and 2030?
- 9. How to Use These Tesla Price Targets
- 10. Tesla Share Price Targets 2035–2050: Long-Term Forecasts
- 11. How to Interpret Long-Term Price Targets
- 12. Practical Investor Checklist: Evaluating Tesla Before Buying
- 13. Conclusion: Can Tesla Deliver Long-Term Shareholder Returns?
- 14. FAQs
- 15. Author
About Tesla, Inc.
Tesla, Inc. is an American electric vehicle and clean energy company headquartered in Austin, Texas. Founded in 2003, the company became one of the most recognized names in electric vehicles under the leadership of CEO Elon Musk. Its mission centers on accelerating the world’s transition to sustainable energy.
Tesla operates across several business areas, including electric vehicles, battery energy storage, solar energy products, charging infrastructure, vehicle software, and artificial intelligence. Its best-known vehicles include the Model 3, Model Y, Model S, and Model X, along with the Cybertruck. The company is also developing autonomous-driving technology, its Robotaxi service, and Optimus humanoid robots.
For investors, the main question is how much of Tesla’s future value will come from selling vehicles and how much could come from newer businesses. Vehicle sales provide an established source of revenue, while autonomy and robotics could create additional growth if Tesla can deliver reliable products at commercial scale.
Investors should also remember that Tesla’s business faces real challenges. Competition from Chinese manufacturers, price cuts, production costs, changing government incentives, and consumer demand can all affect profits. Its future performance will depend not only on technological progress but also on whether these products can generate sustainable earnings and cash flow.
| Details | Information |
|---|---|
| Company Name | Tesla Inc. |
| Business Sector | Tesla officially operates in two primary business segments: Automotive and Energy Generation and Storage, while expanding heavily into autonomous software and robotics. |
| Stock Symbol | NASDAQ: TSLA |
| NASDAQ Status | Listed |
| NSE Listing Status | Not Listed |
| BSE Listing Status | Not Listed |
| Official Website | https://www.tesla.com/ |
| Industry | Automobiles & Auto Parts |
| Sector | Consumer Cyclicals |
| Employees | 134785 |
| Market | United States |
Key Points About Tesla
Tesla’s investment case involves several business segments, markets, and technologies. Understanding these areas helps investors separate the company’s current financial performance from its more uncertain long-term opportunities.
Revenue Breakdown
Tesla generates revenue mainly from automotive sales and leasing, regulatory credits, energy generation and storage, and services and other activities. Automotive operations remain central to the business, but energy storage and services are important because they can diversify revenue beyond vehicle deliveries.
Tesla’s reported Q2 2026 revenue was approximately $28.24 billion, up around 26% year over year. Revenue for the first six months of 2026 was approximately $50.62 billion. These figures provide a useful starting point for assessing growth, but revenue alone does not reveal whether the company is becoming more profitable. Investors must also examine operating margins, free cash flow, and earnings per share.
Tesla’s total annual revenue for FY 2025 was $94.83 billion, while its trailing twelve months (TTM) revenue as of mid-2026 reached $103.62 billion.
Tesla Revenue by Business Segment (FY 2025):
| Business Segment | Revenue in Value | Revenue Share |
|---|---|---|
| Automotive | $69.53 billion | 73.32% |
| Energy Generation and Storage | $12.77 billion | 13.47% |
| Services and Other | $12.53 billion | 13.21% |
Tesla Revenue by Region (FY 2025):
| Counties | Revenue | Revenue Share |
|---|---|---|
| United States | $47.63 billion | 50.23% |
| Other Countries | $26.24 billion | 27.67% |
| China | $20.96 billion | 22.11% |
For example, selling more vehicles at lower prices may increase revenue while reducing profit per vehicle. Conversely, growing energy storage deployments or software-related revenue could improve the business mix if those activities generate attractive margins.
Geographical Concentration
Tesla sells vehicles and energy products in the United States, China, Europe, and other international markets. The US remains an important market, while China is critical both as a major electric vehicle market and as a manufacturing center.
This geographic reach provides growth opportunities but also creates risks. Trade restrictions, tariffs, changes in electric vehicle incentives, currency movements, and differences in local competition can influence demand and profitability.
China is particularly important because Tesla competes with domestic manufacturers such as BYD, which offer a wide range of electric and plug-in hybrid vehicles. European demand is influenced by consumer spending, regulations, incentives, and competition from both established automakers and newer electric vehicle companies.
Employee Base
Tesla employs a large global workforce across vehicle manufacturing, battery production, software development, sales, service, charging infrastructure, and energy operations. Its workforce supports factories, research facilities, and delivery and service networks across several countries.
Employee numbers can change significantly as Tesla expands production, restructures operations, automates factories, or adjusts spending. Investors should therefore use the latest annual report or quarterly filing for a verified employee count rather than relying on older figures.
Staffing also matters financially. Manufacturing productivity, employee costs, engineering talent, and the ability to retain skilled workers can affect production efficiency and the speed at which new technologies reach customers.
Products, Platforms, and Services
Tesla’s business extends beyond its passenger vehicles.
- Electric vehicles: Model 3, Model Y, Model S, Model X, and Cybertruck.
- Energy storage: Powerwall for homes and Megapack for utility-scale projects.
- Solar products: Solar panels and related energy solutions.
- Charging infrastructure: Supercharger stations and charging services.
- Software: Driver-assistance features, connectivity, and vehicle software updates.
- Mobility: Development of autonomous transportation and Robotaxi services.
- Robotics: Optimus, Tesla’s humanoid robot development program.
These businesses have different levels of maturity. Vehicle sales and energy storage already contribute to reported revenue, while the long-term financial value of fully autonomous transportation and humanoid robots remains uncertain.
AI Developments and Robotaxi Plans
Artificial intelligence is central to Tesla’s long-term investment story. The company develops driver-assistance software, neural networks, onboard computing systems, and AI infrastructure intended to support increasingly automated driving.
Its Robotaxi ambitions could eventually create a new transportation business if Tesla can establish safe, reliable, legally permitted, and economically viable autonomous operations. A successful service could generate revenue through passenger fares, fleet utilization, and potentially a wider network of vehicles.
However, technical progress is not the same as commercial success. Robotaxi expansion depends on safety performance, regulatory approval, insurance, operating costs, customer acceptance, and competition. Investors should avoid valuing the business as if large-scale autonomous operations were already fully established.
Tesla is also developing Optimus, a humanoid robot intended for industrial and other applications. The opportunity is significant if robots can perform useful tasks at a competitive cost, but mass production, reliability, customer demand, and actual profit margins remain key questions.
Expansion, Acquisitions, Partnerships, and Recent Deals
Tesla has expanded through manufacturing facilities, battery supply arrangements, charging infrastructure, energy projects, and investments in production technology. Its factories in the United States, China, and Germany support manufacturing closer to major markets.
The company has also pursued partnerships and industry arrangements involving charging standards, battery materials, manufacturing equipment, and supply chains. Such arrangements can improve access to customers or supplies, but they do not automatically translate into higher earnings.
When evaluating recent deals, investors should distinguish between signed agreements, announced plans, pilot projects, and completed commercial operations. These are not equivalent. A planned factory or proposed product launch should not be counted as current production or guaranteed revenue.
Tesla’s acquisition history and related-party transactions also deserve careful attention. Material transactions should be checked against official company disclosures, particularly where they involve substantial spending, strategic assets, or potential conflicts of interest.
For the latest verified information, consult Tesla Investor Relations and the company’s SEC filings. These primary sources are more reliable than treating market rumors or unconfirmed announcements as completed business developments.
Company Fundamentals: Revenue, Earnings, and Valuation
Company fundamentals help investors understand whether a stock’s price is supported by its financial performance. For Tesla, the most important factors include revenue growth, vehicle profitability, operating expenses, cash flow, capital spending, and the potential contribution of energy and software businesses.
Revenue and Earnings Performance
Tesla’s annual financial results show why investors need to look beyond its reputation as a technology company. According to its 2025 Form 10-K, Tesla reported total revenue of approximately $94.83 billion in 2025, compared with $97.69 billion in 2024. Automotive revenue, including leasing and regulatory credits, fell from $77.07 billion to $69.53 billion. Meanwhile, energy generation and storage revenue increased from approximately $10.09 billion to $12.77 billion.
Source: sec.gov
These figures highlight two different trends. The automotive business experienced pressure, while energy storage continued to expand. Whether the energy segment can grow fast enough to offset weaker vehicle economics is an important question for long-term investors.
Tesla’s total gross margin was approximately 18.0% in 2025, compared with 17.9% in 2024. However, the automotive and services segment’s gross margin declined from 16.9% to 16.2%. The energy generation and storage segment’s gross margin increased from 26.2% to 29.8%. These differences matter because revenue from a higher-margin business can contribute more gross profit per dollar of sales, although operating expenses and investment requirements must also be considered.
Operating Margin and Free Cash Flow
Operating margin measures the share of revenue remaining after operating expenses. Free cash flow generally represents cash generated from operations after capital expenditure, making it useful for judging whether a company can fund expansion without relying heavily on additional financing.
Tesla must balance investment in factories, battery production, computing infrastructure, autonomy, and robotics against the need to maintain healthy cash generation. Heavy investment can support future growth, but it can also reduce near-term free cash flow.
Investors should monitor the following figures in each Tesla earnings report:
- Revenue growth: Is demand increasing without excessive discounting?
- Automotive gross margin: Are vehicle sales becoming more profitable?
- Operating margin: Are operating expenses growing faster than revenue?
- Free cash flow: Can Tesla finance expansion while generating cash?
- Capital expenditure: How much cash is being committed to future projects?
- Diluted earnings per share: Are profits increasing on a per-share basis?
Tesla’s Q3 2026 financial results are scheduled for October 21, 2026. Until those results are released, investors should not treat third-quarter earnings estimates as reported financial figures.
Tesla Stock Valuation and the P/E Ratio
The price-to-earnings ratio, or P/E ratio, compares a company’s share price with its earnings per share. It is one way to assess how much investors are paying for each dollar of earnings.
For example, if a company trades at $400 per share and earns $4 per share annually, its P/E ratio is 100. If its share price stays at $400 but earnings rise to $8 per share, the ratio falls to 50. The reverse can happen when earnings decline.
Tesla’s valuation is difficult to compare directly with that of traditional automakers because some investors assign value to its potential in autonomous driving, AI, energy storage, and robotics. Those opportunities may justify a higher valuation if they eventually produce substantial, recurring profits.
However, future potential is not the same as current earnings. A high TSLA P/E ratio leaves less room for disappointment if vehicle sales slow, profit margins fall, or new technologies take longer than expected to become commercially successful.
Investors should compare Tesla’s trailing P/E, forward P/E, enterprise value, free cash flow, and expected earnings growth. They should also test whether the valuation remains reasonable under more conservative assumptions rather than relying entirely on optimistic projections.
What Wall Street Analysts Expect
Analyst price targets are estimates, not promises. As of October 2026, Stock Analysis reported an average one-year target of approximately $396.57 from 44 analysts, with a low estimate of $128.11 and a high estimate of $600. The provider showed a consensus rating of Buy. Other market-data providers can report different averages because their coverage and update times vary.
Source: Stockanalysis.com: Forecast
This wide range reflects different views about Tesla’s earnings prospects and future businesses. Optimistic analysts may place more value on robotaxis, AI, and energy growth. More cautious analysts may focus on vehicle margins, competition, high capital expenditure, and the risk that new projects fail to generate expected returns.
A useful way to read analyst research is to ask three questions: What earnings does the analyst expect? What valuation multiple is being applied? What business assumptions must come true for the target to be reached?
The Wall Street consensus rating is a starting point for research, not a substitute for independent analysis. An investor should also examine whether the analyst’s target has been updated following the latest financial results and major business developments.
Technical Analysis of Tesla Stock
Fundamental analysis focuses on business performance and value, while technical analysis examines price movements, trading volume, trends, and market momentum. Technical indicators can help investors plan entries and exits, but they cannot reliably predict the share price decades into the future.
Because market prices change throughout the trading day, technical levels must be checked against a current price chart before being used in an investment decision.
Moving Averages and Trend Direction
The 50-day moving average measures the average closing price over roughly ten trading weeks. The 200-day moving average covers a much longer period and is commonly used to assess the broader trend.
- When the share price stays above both averages, the trend may be positive.
- When the price falls below both averages, selling pressure may be increasing.
- When the 50-day average crosses above the 200-day average, traders often call it a golden cross.
- When the 50-day average crosses below the 200-day average, it is commonly called a death cross.
These signals are not guaranteed. A stock can rise or fall sharply after a moving-average crossover, particularly when news changes investor expectations.
Relative Strength Index and Trading Volume
The Relative Strength Index (RSI) measures recent price momentum on a scale from 0 to 100. Readings above 70 are often described as overbought, while readings below 30 are often described as oversold. These thresholds indicate conditions to investigate rather than automatic buy or sell signals.
Trading volume can provide additional context. A price breakout accompanied by strong volume may indicate broader participation from buyers, while a breakout on weak volume may be less convincing.
Tesla can experience large price movements following delivery figures, earnings announcements, regulatory decisions, or developments involving autonomous driving. Investors should avoid making a decision based on a single indicator.
Support, Resistance, and Risk Management
Support refers to a price area where buying has previously emerged, while resistance refers to an area where selling has limited gains. These levels are not fixed and may change as new information reaches the market.
Investors can use technical analysis to plan position sizes and identify levels at which their original investment thesis would need to be reconsidered. Long-term investors, however, should not confuse short-term chart movements with lasting changes in business value.
For updated charts and indicators, investors can use established charting platforms such as TradingView or review market data through Nasdaq. Always verify the chart’s date and trading session before using a quoted level.
Tesla vs. BYD: Competitive Position
Tesla faces competition from established automakers and newer electric vehicle manufacturers. BYD is especially important because it has a large presence in China and sells both battery-electric vehicles and plug-in hybrid vehicles. Other competitors include major global carmakers that are investing in electric platforms, batteries, and software.
Tesla’s strengths include its established brand, charging network, software capabilities, manufacturing experience, and direct customer relationships. Its energy storage operations also give it a business opportunity beyond passenger vehicles.
BYD competes through a broad product range, battery expertise, manufacturing scale, and pricing. In markets where customers are highly price-sensitive, these advantages can put pressure on Tesla’s sales and margins.
The comparison is not simply about which company sells more vehicles. Investors should consider vehicle profitability, product availability, regional sales, battery costs, energy storage, software revenue, and future investment requirements. Different companies also report vehicle sales and financial results over different periods, so comparisons should use matching reporting dates.
For Tesla, the key challenge is to defend its automotive position while building new sources of profit. If it succeeds, it could become less dependent on vehicle sales. If it does not, investors may need to reconsider how much they are willing to pay for its future technology opportunities.
Pros and Cons of Investing in Tesla
Tesla offers several potential advantages, but its risks are significant. Investors should weigh both sides before deciding whether the stock fits their financial goals, investment horizon, and tolerance for volatility.
Advantages of Tesla Stock
- Strong global brand: Tesla is widely recognized in the electric vehicle market, giving it an established customer base and international presence.
- Energy storage growth: Powerwall and Megapack give Tesla exposure to home energy storage and large-scale electricity storage projects.
- Software and AI opportunities: Driver-assistance software, autonomous driving, and robotics could create additional revenue streams if they become commercially successful.
- Manufacturing experience: Tesla has developed large-scale vehicle and battery manufacturing operations across multiple regions.
- Charging infrastructure: Its Supercharger network can support customer convenience and create opportunities to serve other electric vehicle brands.
- Potential operating improvements: Lower production costs, higher factory utilization, and better product mix could improve profitability if demand remains healthy.
Disadvantages and Risks
- High valuation: The stock can be vulnerable to a sharp correction if earnings growth falls short of investor expectations.
- Intense competition: BYD and other automakers can compete aggressively on price, product features, and market share.
- Pressure on vehicle margins: Price reductions and incentives can help maintain demand but may reduce profit per vehicle.
- Execution risk: Robotaxis and humanoid robots may take longer to become profitable than investors expect.
- Regulatory uncertainty: Autonomous-driving rules, safety requirements, trade policies, and changing government incentives can affect growth.
- High investment needs: Expanding factories, computing infrastructure, and new products requires substantial capital.
- Leadership and governance risk: Investors must consider the effects of management priorities, key-person dependence, and decisions involving related businesses.
Recent reporting has highlighted the debate over Tesla’s planned AI-related spending. Some analysts have expressed concern that higher capital expenditure could weaken free cash flow, even as others see potential value in autonomous driving and related technologies.
Source: Barrons
Should I Buy Tesla Stock?
Whether Tesla belongs in a portfolio depends on the investor’s goals and the price paid. Investors who believe Tesla can build profitable autonomous transportation, expand energy storage, and improve manufacturing economics may view the company as a long-term growth opportunity.
More cautious investors may prefer to wait for clearer evidence of sustained earnings growth, stronger vehicle margins, and measurable returns from new investments.
Before investing, consider the following checklist:
- Review the latest financial statements and earnings guidance.
- Compare the current valuation with realistic earnings estimates.
- Understand how much of the investment case depends on unproven technology.
- Consider the possibility of a substantial share-price decline.
- Avoid concentrating too much of a portfolio in one company.
- Reassess the investment thesis when material financial or business information changes.
A strong company is not automatically a strong investment at every price. The price paid, future earnings, competitive position, and risks all matter.
Tesla Share Price Targets 2026–2030
Forecasting Tesla’s share price requires more than extending its historical growth rate into the future. Investors must consider vehicle deliveries, selling prices, profit margins, energy storage growth, operating expenses, capital spending, and the commercial progress of autonomous driving and artificial intelligence.
The following projections are illustrative scenario estimates, not guaranteed outcomes or verified Wall Street consensus figures. They are designed to show how Tesla’s valuation could change under different business conditions. The figures are expressed in US dollars per share and assume no stock split or other corporate action that would change the quoted per-share amounts.
The low, average, and high figures represent bearish, base-case, and bullish scenarios, respectively. They are not statistical confidence intervals, and the average is not necessarily the midpoint of the other two estimates.
Company Share Price Target 2026
Tesla’s 2026 outlook depends on whether vehicle demand, energy storage, and new technology investments can support profitable growth.
The company reported approximately $28.24 billion in revenue for Q2 2026, up around 26% year over year, and 486,532 vehicle deliveries for Q3 2026. Its third-quarter financial results are scheduled for October 21, 2026, so the final quarterly revenue and earnings figures are not yet available as of October 10.
For the remainder of 2026, the main question is whether Tesla can turn its reported business growth into stronger earnings and cash flow. A bullish outcome would likely require resilient vehicle demand, healthy energy storage growth, and credible progress in autonomy.
A bearish outcome could result from weaker margins, increased competition, or higher-than-expected investment costs.
| Year | Low approx. | Average approx. | High approx. |
|---|---|---|---|
| 2026 | $250 | $400 | $550 |
What could support these estimates?
- Bearish case — $250: Vehicle margins weaken, competition increases, or investors reduce the premium they assign to Tesla’s future technology businesses.
- Base case — $400: Automotive performance remains broadly resilient, energy storage grows, and the company maintains a reasonable path toward improved profitability.
- Bullish case — $550: Investors gain confidence in earnings growth, energy deployments, and the commercial potential of autonomous driving.
- Key evidence to monitor: Q3 results, full-year delivery figures, automotive gross margin, free cash flow, and management’s 2027 outlook.
These numbers are scenario anchors, not a claim that the stock will finish 2026 at any particular price. Investors should compare them with the current market price and updated analyst estimates before drawing conclusions about potential returns.
Company Share Price Target 2027
The 2027 outlook will depend on Tesla’s ability to expand its business while managing costs. If vehicle production and deliveries grow without requiring substantial price cuts, automotive revenue could improve. Higher energy storage deployments could also help diversify the company’s earnings.
A central issue is whether Tesla’s Robotaxi rollout develops into a commercially useful service. A limited service, a successful regional expansion, and a large-scale autonomous network would have very different financial implications. Investors should not value all three outcomes in the same way.
| Year | Low approx. | Average approx. | High approx. |
|---|---|---|---|
| 2027 | $220 | $450 | $700 |
What could support these estimates?
- Bearish case — $220: Vehicle price competition intensifies, earnings disappoint, or higher spending weighs on free cash flow.
- Base case — $450: Deliveries and energy revenue grow, while the company continues investing in AI without a severe decline in financial strength.
- Bullish case — $700: Strong earnings growth combines with convincing evidence that autonomous transportation can become a scalable business.
- Key evidence to monitor: Vehicle demand by region, operating margin, diluted earnings per share, and the economic performance of any expanding Robotaxi operations.
The base case assumes that Tesla remains a growing business but does not automatically become a dominant autonomous transportation platform. That distinction is important because the market may already price in some future success.
Company Share Price Target 2028
By 2028, Tesla’s valuation could depend more heavily on the balance between its established businesses and its newer technology projects. Vehicle sales may remain the main source of revenue, but energy storage, software, charging services, and autonomous transportation could influence how investors value the company.
The bullish scenario assumes that Tesla makes measurable progress toward generating revenue and profits from new technologies. The bearish scenario assumes that those businesses develop more slowly than expected, leaving investors to value Tesla primarily on its automotive and energy operations.
| Year | Low approx. | Average approx. | High approx. |
|---|---|---|---|
| 2028 | $200 | $500 | $850 |
What could support these estimates?
- Bearish case — $200: Vehicle margins remain under pressure, competing manufacturers gain ground, or new business investments produce weak returns.
- Base case — $500: Automotive and energy businesses expand, and the company makes gradual progress in software and autonomous-driving capabilities.
- Bullish case — $850: Stronger earnings and a credible path toward profitable autonomous transportation lead investors to assign Tesla a higher valuation.
- Key evidence to monitor: Energy gross margin, capital expenditure, software-related revenue, fleet utilization where applicable, and cash generated after investment spending.
A rising share price would need financial support over time. Even if Tesla’s products improve, the stock could underperform if its earnings do not grow quickly enough to justify the valuation investors are paying.
Company Share Price Target 2029
The 2029 outlook introduces a wider range of possible outcomes because small differences in annual growth can compound over several years. If Tesla expands its production capacity, improves manufacturing efficiency, and increases the contribution of higher-margin businesses, earnings could grow substantially.
However, the company could also face slower demand, new competitors, or higher costs associated with building out AI infrastructure. Investors should therefore distinguish between business growth and per-share value creation. Issuing additional shares, for example, can dilute existing shareholders even when the overall business becomes larger.
| Year | Low approx. | Average approx. | High approx. |
|---|---|---|---|
| 2029 | $180 | $550 | $1,000 |
What could support these estimates?
- Bearish case — $180: Automotive profitability deteriorates, technology spending rises faster than earnings, or the market assigns a lower valuation multiple.
- Base case — $550: Tesla maintains growth across vehicles and energy while improving earnings and cash generation.
- Bullish case — $1,000: Multiple businesses become meaningful profit contributors, and investors expect sustained growth from autonomy, software, and robotics.
- Key evidence to monitor: Return on invested capital, free cash flow per share, energy deployments, vehicle pricing, and the commercial success of new products.
The high estimate is an optimistic scenario, not a prediction that Tesla must reach $1,000. It requires a combination of strong financial performance and a market willing to pay a premium for future growth.
Company Share Price Target 2030
The 2030 forecast is an important long-term checkpoint because it allows time for Tesla’s energy business, manufacturing strategy, and AI initiatives to develop. By this stage, investors should have substantially more evidence about which opportunities can generate recurring revenue and which remain expensive development projects.
The strongest bullish case assumes that Tesla improves its vehicle economics and builds profitable businesses around energy and autonomous transportation. The bearish case assumes that traditional vehicle competition remains intense and that the company’s newer ventures do not contribute enough earnings to support its valuation.
| Year | Low approx. | Average approx. | High approx. |
|---|---|---|---|
| 2030 | $150 | $600 | $1,200 |
What could support these estimates?
- Bearish case — $150: Earnings growth remains weak, automotive margins decline, or investor enthusiasm for future technologies fades.
- Base case — $600: Tesla grows revenue across vehicles and energy, generates stronger cash flow, and demonstrates practical progress in autonomous driving.
- Bullish case — $1,200: Tesla builds a much larger earnings base and establishes commercially successful autonomous transportation or robotics operations.
- Key evidence to monitor: Long-term earnings growth, diluted share count, energy profitability, autonomy-related economics, and the relationship between valuation and free cash flow.
A stock price of $600 or $1,200 would not, by itself, prove that Tesla had become a better investment. Investors must compare the price with the earnings and cash flow supporting it, as well as the return available from other investments.
What Could Change Tesla’s Forecasts Between 2026 and 2030?
The price scenarios above depend on a small number of important business drivers. Investors should review these drivers regularly because a change in earnings expectations can affect Tesla’s valuation even when its products and technology remain attractive.
1. Vehicle Deliveries and Pricing
Tesla delivered 486,532 vehicles in Q3 2026, exceeding published analyst expectations of approximately 462,000. However, deliveries were down roughly 2% year over year.
The company also deployed 13.7 GWh of energy storage products during the quarter. These figures suggest that vehicle demand and energy growth need to be assessed separately rather than assuming that strength in one business guarantees strength in the other.
Source: Tesla Third Quarter 2026
Higher deliveries can support revenue, but price reductions can limit the benefit. Investors should examine both the number of vehicles sold and the profit earned from each sale.
2. Earnings Estimates and Capital Spending
Tesla’s future valuation depends on its ability to turn revenue into earnings. If analysts raise their Tesla EPS estimates because costs decline or new businesses generate revenue, the stock could become easier to justify at a given price. If earnings estimates fall, even a stable share price can leave the stock trading at a higher P/E ratio.
Capital spending is another important factor. Barron’s reported in October 2026 that BNP Paribas maintained a Sell rating with a $268 target, citing concerns about higher investment spending and pressure on future cash flow. Baird maintained a Buy rating with a $475 target, while JPMorgan retained a Hold rating with a $415 target.
These differing views illustrate how analysts can interpret the same company very differently.
Source: Barron’s – Tesla Earnings Estimate
Investors should check the date and assumptions behind every target. A price target issued before an earnings release may no longer reflect the analyst’s latest estimates.
3. Robotaxi, AI, and Robotics
Tesla’s long-term growth case could improve if autonomous transportation becomes a profitable service rather than simply a technology demonstration. Similarly, energy storage could become increasingly important if demand for grid-scale batteries and electricity infrastructure continues to expand.
However, these opportunities should be evaluated using evidence such as commercial deployment, customer demand, revenue, operating costs, safety performance, and regulatory approval. Announced plans and technical demonstrations are not equivalent to sustained profits.
4. Valuation Multiples and Investor Expectations
A stock’s value depends on both its expected earnings and the multiple investors are willing to pay for those earnings. For example, a company earning $10 per share would trade at $500 under a 50-times P/E multiple, but at $250 under a 25-times multiple.
This simplified example shows why a business can improve while its share price falls. If Tesla’s earnings rise but its valuation multiple declines more sharply, shareholders may still experience negative returns.
For this reason, investors should evaluate each annual scenario using three questions:
- How much earnings growth is expected?
- What valuation multiple is reasonable for that level of growth?
- What evidence would show that the assumptions are becoming more or less likely?
How to Use These Tesla Price Targets
These annual estimates are best treated as a framework for evaluating possibilities rather than as a schedule of expected market prices. The low, average, and high cases are deliberately spread apart because Tesla’s valuation depends on uncertain future earnings and technology outcomes.
Before making an investment decision, compare the scenarios with the current share price, the latest analyst estimates, and the company’s reported results. Also account for stock splits, dilution, taxes, and transaction costs when calculating actual investment returns.
The next part will extend the analysis to 2035, 2040, 2045, and 2050. Those forecasts require even wider scenario ranges because competition, technology, regulation, and the economics of autonomous transportation may change substantially over decades.
Tesla Share Price Targets 2035–2050: Long-Term Forecasts
Predicting Tesla’s share price beyond 2030 is much more uncertain than estimating its performance over the next year or two. Over two decades, the company could develop profitable businesses in autonomous transportation, energy storage, AI computing, and robotics.
It could also face new competitors, changing regulations, weaker demand, or technology that does not become commercially viable.
The following long-term estimates are illustrative scenarios developed for this article, not published Wall Street consensus forecasts. They use US dollars per share and assume no stock split or other corporate action that changes the per-share figures. The estimates are not guarantees, and the high scenarios require substantial business success.
Company Share Price Target 2035
By 2035, Tesla could be a more diversified company if it successfully expands beyond vehicle manufacturing. Energy storage could become a larger source of revenue, while autonomous transportation and software could add new income streams. However, the size and profitability of these businesses will depend on customer demand, regulation, competition, and execution.
The base case assumes Tesla grows its established businesses and makes measurable progress in newer areas without assuming that every ambitious project succeeds. The bullish case requires much stronger earnings growth and evidence that Tesla can earn attractive returns from AI and autonomous transportation.
| Year | Low approx. | Average approx. | High approx. |
|---|---|---|---|
| 2035 | $120 | $800 | $1,800 |
What could support these estimates?
- Bearish case — $120: Competition limits vehicle profitability, new ventures remain expensive, or Tesla’s valuation multiple contracts.
- Base case — $800: Vehicles and energy storage continue to grow, with additional earnings from software and selected autonomous-driving services.
- Bullish case — $1,800: Tesla develops multiple profitable businesses and produces substantial, sustained growth in earnings per share.
- Key factors to monitor: Free cash flow, operating margins, market share, energy storage profitability, and the actual financial contribution of autonomous services.
These scenarios illustrate how different assumptions can lead to very different outcomes. They should not be interpreted as a prediction that Tesla will trade near $800 or $1,800 in 2035.
Company Share Price Target 2040
By 2040, the electric vehicle market may be considerably more mature, and competition could come from manufacturers that do not yet have a major presence today.
Tesla’s long-term value will therefore depend on more than selling electric vehicles. Its ability to retain customers, control costs, improve battery technology, and generate revenue from energy and software could become increasingly important.
Autonomous transportation could have a meaningful economic role if vehicles can operate safely and profitably under applicable laws.
However, competitors may develop comparable technology, and regulators may require significant changes to how autonomous fleets operate. Even a successful Robotaxi service would need to generate enough profit to justify the investment required to build and maintain it.
| Year | Low approx. | Average approx. | High approx. |
|---|---|---|---|
| 2040 | $100 | $1,000 | $2,500 |
What could support these estimates?
- Bearish case — $100: Tesla loses market share, experiences prolonged margin pressure, or fails to generate significant profits from newer technologies.
- Base case — $1,000: The company remains competitive in vehicles and energy while adding profitable software or autonomous services.
- Bullish case — $2,500: Tesla builds a large, profitable technology and transportation ecosystem with sustained earnings growth.
- Key factors to monitor: Long-term earnings per share, return on invested capital, competitive advantages, and the cost of maintaining technological leadership.
The high case depends on major commercial success over many years. It should not be used as a reason to buy shares today without evaluating the present valuation and the possibility of permanent capital loss.
Company Share Price Target 2045
The 2045 forecast requires assumptions about technology, consumer behavior, the energy industry, and the competitive environment more than 18 years from now.
Tesla could benefit if electric transportation becomes increasingly common and demand for grid-scale storage rises. Its robotics program could also create opportunities if businesses adopt humanoid robots for useful tasks at a competitive cost.
However, the company may need to invest continuously to maintain its position. Today’s manufacturing strengths may not guarantee a lasting advantage if competitors develop better batteries, lower-cost vehicles, more capable AI systems, or superior production methods.
| Year | Low approx. | Average approx. | High approx. |
|---|---|---|---|
| 2045 | $80 | $1,250 | $3,500 |
What could support these estimates?
- Bearish case — $80: Profit growth weakens, competition erodes pricing power, or large technology investments fail to earn attractive returns.
- Base case — $1,250: Tesla retains a competitive position in vehicles and energy while developing additional profitable services.
- Bullish case — $3,500: Tesla becomes a major supplier of autonomous transportation, energy infrastructure, and commercial robotics, with strong per-share earnings growth.
- Key factors to monitor: Sustainable competitive advantages, product reliability, research spending, customer adoption, and dilution from future share issuance.
The large gap between the low and high estimates is intentional. Forecasting a company’s share price almost two decades ahead involves substantial uncertainty, and precise-looking numbers can create a false sense of confidence.
Company Share Price Target 2050
The 2050 outlook is the most speculative part of this analysis. By then, the automotive industry, energy systems, computing technology, and transportation services could look very different from today’s markets. Tesla may become a much larger company, remain primarily an automaker and energy supplier, or lose ground to new competitors.
A bullish outcome would require Tesla to build durable businesses that generate strong profits for many years. A base-case outcome assumes continued relevance and gradual diversification, while the bearish case considers the possibility that Tesla fails to sustain its current competitive position.
| Year | Low approx. | Average approx. | High approx. |
|---|---|---|---|
| 2050 | $50 | $1,500 | $5,000 |
What could support these estimates?
- Bearish case — $50: Long-term competitive pressure, weak profitability, or a lower valuation multiple substantially reduces the stock’s value.
- Base case — $1,500: Tesla remains a major vehicle and energy company, expands selected technology businesses, and produces sustained earnings growth.
- Bullish case — $5,000: Tesla develops several large and profitable businesses and maintains a strong competitive position for decades.
- Key factors to monitor: Long-term profitability, earnings per share, capital allocation, technological leadership, and the company’s ability to create value for shareholders.
The $5,000 scenario is an optimistic illustration, not an evidence-based Wall Street forecast. A price target this far into the future should never be treated as a reliable estimate of what investors will actually receive.
How to Interpret Long-Term Price Targets
A high future share price does not automatically mean a high investment return. The result depends on the purchase price, the time taken to reach the target, dividends if any, share dilution, and the risk of the forecast failing.
For example, suppose an investor buys a share for $400 and it reaches $1,500 after 24 years. Ignoring dividends, taxes, and transaction costs, the annualized price return would be approximately 5.7%. This is much lower than the total price increase of 275% might initially suggest.
The calculation is:
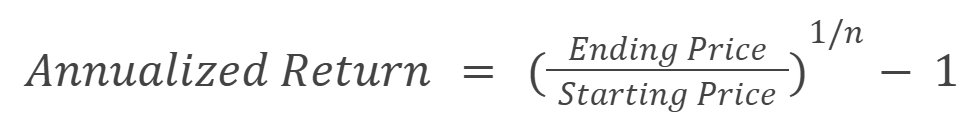
Here, (n) represents the number of years invested. For a 24-year holding period, the result is approximately 5.7% annually.
Investors should also consider inflation. A future share price of $1,500 will not have the same purchasing power in 2050 as $1,500 has today. For long-term planning, nominal price targets should be evaluated alongside inflation-adjusted returns.
Finally, stock splits can change the quoted share price without changing the underlying value of an investor’s holdings at the time of the split. Any long-term forecast should therefore be interpreted consistently with Tesla’s share count and corporate actions.
Practical Investor Checklist: Evaluating Tesla Before Buying
Before investing, use the following checklist to turn a general forecast into a more disciplined decision.
Pre-investment checklist
- Read Tesla’s latest quarterly report and annual filing.
- Compare actual vehicle deliveries with market expectations.
- Check automotive gross margin and operating margin.
- Review free cash flow and planned capital expenditure.
- Compare current valuation with forward earnings estimates.
- Assess the actual commercial progress of Robotaxi and AI projects.
- Review competition from BYD and other automakers.
- Consider downside scenarios and portfolio concentration.
- Check the latest analyst upgrades, downgrades, and price targets.
- Set an investment horizon and review the thesis periodically.
Useful Financial Research Tools
Investors can use the following resources to verify the figures and perform their own analysis:
- Tesla Investor Relations — official financial results, presentations, and company announcements.
- SEC company filings — annual reports, quarterly filings, and disclosures.
- Nasdaq TSLA page — stock information and market data.
- TradingView — price charts, moving averages, RSI, and other technical indicators.
- Stock Analysis — analyst price targets and consensus estimates.
For additional portfolio calculations, look for relevant share-price target, P/E ratio, CAGR, and investment-return calculators on StockMarketor.com, verifying the available tool and its assumptions before relying on its results.
A calculator can help compare scenarios, but it cannot establish whether Tesla will achieve a particular earnings level or valuation multiple.
Conclusion: Can Tesla Deliver Long-Term Shareholder Returns?
Tesla has several possible paths to growth. Its established electric vehicle business, expanding energy storage operations, charging network, and software capabilities provide a foundation. Its ambitions in AI, Robotaxi services, and humanoid robotics offer additional opportunities, but those businesses must demonstrate that they can generate sustainable profits.
The 2026–2030 scenarios show how changes in vehicle economics, earnings, and valuation could lead to different share prices over the next several years. The 2035–2050 projections are considerably less certain because they depend on developments that cannot be reliably predicted today.
For investors, the most important task is not to find the highest possible target. It is to determine what Tesla is worth under reasonable assumptions, identify what could go wrong, and decide whether the potential return justifies the risk.
Review financial statements, compare analyst estimates, monitor business execution, and reassess assumptions as new information becomes available. A disciplined investment decision should be based on business performance, valuation, and risk management, not on the promise of a particular future share price.
References and editorial notes
The article’s financial facts and forecasting framework should be checked against these primary and supporting sources before publication:
- Tesla Investor Relations — official company results and announcements.
- Tesla’s Q3 2026 delivery and deployment release — reported vehicle deliveries and energy storage deployments.
Tesla Investor Relations - Tesla’s 2025 Form 10-K — audited annual financial statements and risk disclosures.
- Tesla analyst forecasts — dated consensus information and analyst target ranges.
Disclaimer: This article is for educational and informational purposes only. The long-term price ranges are illustrative estimates based on stated assumptions, not personalized investment advice or guaranteed returns. Analyst targets and technical indicators change over time. Verify current financial data and consider consulting a qualified financial professional before making investment decisions. Remember, the stock price targets may vary depending on multiple scenarios including stock price splits. So, keep an eye on such scenarios.
FAQs
What is the Tesla stock forecast for 2026?
Tesla’s 2026 outlook depends on vehicle deliveries, profit margins, energy storage growth, and investment in AI-related businesses. The illustrative scenarios in this article range from $250 in the bearish case to $550 in the bullish case, with a base-case estimate of $400.
These are scenario estimates, not a guarantee or an official analyst consensus. Investors should compare them with the latest market price and financial results.
What is the TSLA price target for 2027?
The illustrative 2027 scenarios are $220 for the low case, $450 for the base case, and $700 for the high case. Achieving the upper end would likely require strong earnings growth and meaningful commercial progress in autonomous driving or other newer businesses.
A weaker automotive market or higher investment costs could push the stock below the base case.
Can Tesla stock reach $1,000 by 2030?
Tesla could theoretically reach $1,000 by 2030, but doing so would require a substantial increase in its market value. The result would depend on earnings growth, the number of shares outstanding, and the valuation multiple investors assign to those earnings.
Strong performance in vehicles, energy storage, and autonomous services could help, but the outcome is uncertain. A high share price alone does not demonstrate that the stock is fairly valued.
Can Tesla stock reach $5,000 by 2050?
A $5,000 share price by 2050 is an optimistic scenario rather than a reliable forecast. It would likely require Tesla to become a much larger and more profitable business over several decades.
Competition, dilution, regulation, inflation, and changing technology could all affect the result. Investors should also account for stock splits, which can change the quoted share price without creating additional economic value.
What is the Wall Street consensus rating for Tesla?
The consensus rating varies by data provider and date. A published Stock Analysis snapshot in October 2026 showed a Buy consensus from 44 analysts and an average one-year target of approximately $396.57.
However, the range extended from $128.11 to $600, showing substantial disagreement. Investors should check the latest analyst forecast compilation before using a consensus figure.
Is Tesla stock overvalued?
Whether Tesla is overvalued depends on its current price relative to future earnings and cash flow. Investors who expect rapid growth in autonomous transportation, AI, and energy may justify a higher valuation than investors who focus mainly on vehicle manufacturing.
However, a high valuation increases the risk of a decline if expected growth does not materialize. Comparing forward earnings estimates, free cash flow, and valuation multiples under different scenarios can help investors assess the risk.
Should I buy Tesla stock for the long term?
Tesla may suit investors who can tolerate significant price volatility and believe the company can expand its profitable businesses over many years. More cautious investors may prefer to wait for clearer evidence of stronger margins, sustainable cash generation, and commercial success in autonomous driving.
The decision should reflect personal financial goals, risk tolerance, diversification, and the price paid. No forecast can guarantee a positive return.
How do Tesla earnings reports affect the share price?
Tesla’s earnings reports can move the stock when actual results differ from investor expectations. Revenue, earnings per share, automotive gross margin, free cash flow, vehicle deliveries, and management guidance can all affect sentiment.
The share price may decline even when revenue increases if profit margins weaken or future guidance disappoints. Investors should compare reported figures with the estimates that were in place before the announcement.
What could cause a Tesla stock upgrade or downgrade?
A TSLA upgrade or downgrade may follow changes in earnings forecasts, vehicle demand, margins, competition, capital expenditure, or expectations for new technologies. Analysts may raise their targets when they expect stronger profits or assign more value to future business opportunities.
They may lower them when risks increase or valuations appear difficult to justify. An analyst rating is an opinion based on assumptions, so investors should read the reasoning rather than follow the rating alone.
Which factors matter most when evaluating Tesla's future share price?
The most important factors include vehicle deliveries, average selling prices, automotive profitability, energy storage growth, capital spending, and earnings per share. Investors should also assess the progress of autonomous driving and robotics without assuming those projects will automatically become profitable.
Competition, regulatory changes, and the valuation multiple can have a major effect on returns. For long-term decisions, reported financial performance is more useful than relying on a distant price target alone.
Author
-
View all posts
Sachin Ramdurg, the Founder and CEO of AllStockShare.com, is an accomplished investor and entrepreneur with over 8 years of experience in stock market investing.
Coming from an engineering background, Sachin combines his analytical mindset with his passion for entrepreneurship and investment strategies to deliver unique and effective insights to the investing community.

Related posts:
 Amara Raja Batteries Share Price Target 2024, 2025, 2030, 2040, 2050 | Amara Raja Batteries Ltd
 Salasar Techno Share Price Target 2024, 2025, 2030, 2040, 2050 | Salasar Share Price Target
 Rattan Power Share Price Target 2024, 2025, 2030, 2040, 2050 | RattanIndia Power Share Price Target
 Salzer Electronics Share Price Target 2024, 2025, 2030, 2040, 2050 | Salzer Share Price Target
 Mazagon Dock Share Price Target 2024, 2025, 2030, 2040, 2050 | Mazagon Dock Shipbuilders Share Price Target
 Enviro Infra Share Price Target 2024, 2025, 2030, 2040, 2050 | Enviro Infra Engineers Share Price Target
 Apollo Tyres Share Price Target 2024, 2025, 2030, 2040, 2050 | Apollo Tyres Limited Share Price Target
 Coal India Share Price Target 2024, 2025, 2030, 2040, 2050 | Coal India Ltd Share Price Target